
How the Appraisal Clause Works in an Arkansas Policy
A plain-English walk through the appraisal condition found in most Arkansas property policies, and the mistakes that weaken it.
Independent appraisal · All 75 counties
Your insurer agreed the damage is covered, but the check won’t pay for the repair. Arkansas Insurance Appraiser builds an independent, line-by-line valuation of the loss and takes it through the appraisal process written into your policy.
Covered is not the same as paid
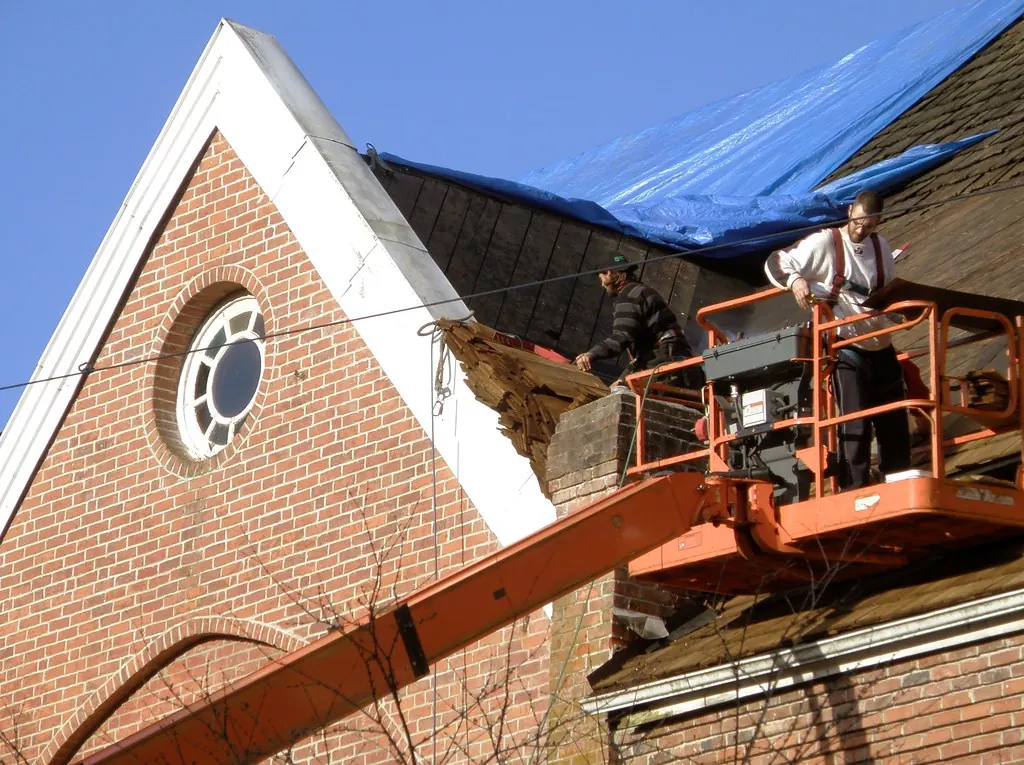
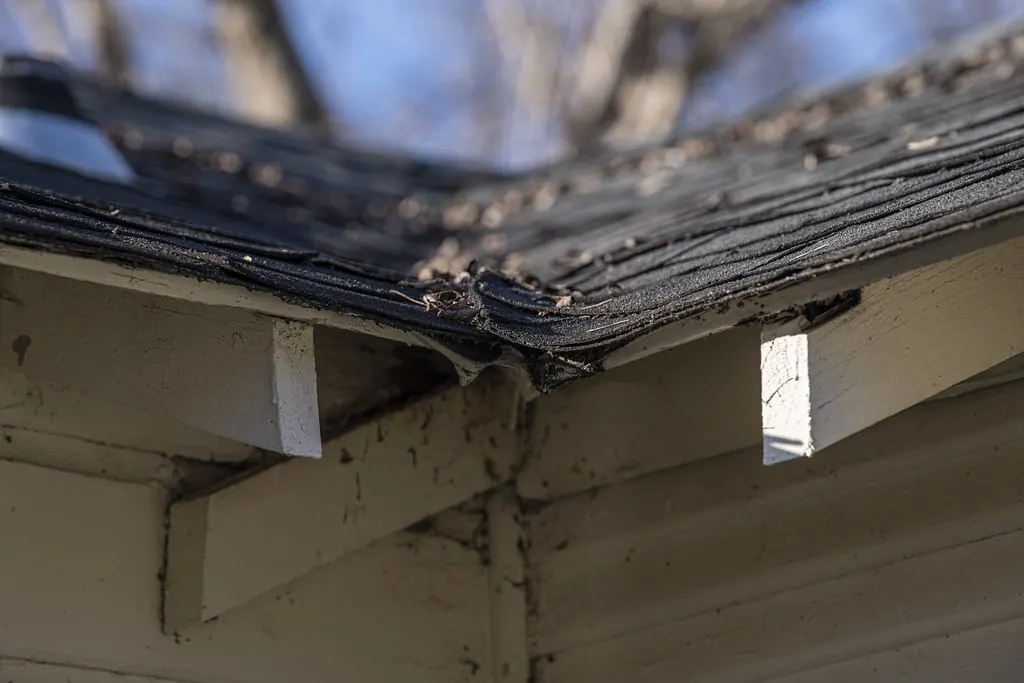
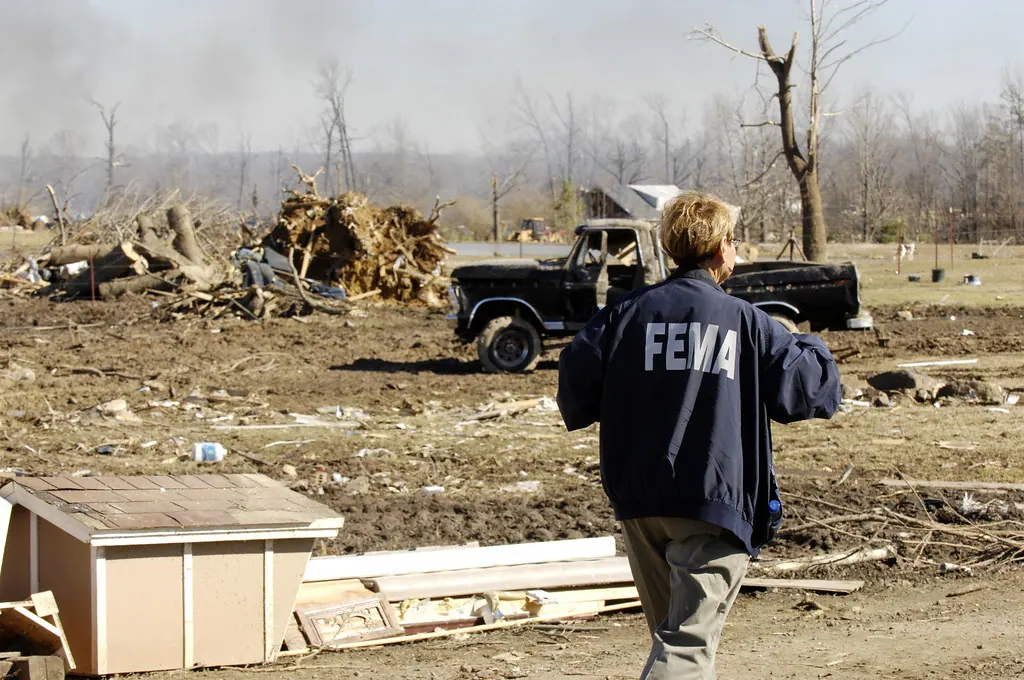
Most underpaid claims in Arkansas aren’t denied. They’re short: a roof slope priced as a repair, a hallway of flooring left out, drip edge and ridge vent missing, depreciation taken on items that shouldn’t lose that much value. An Arkansas Insurance Appraiser is there to close the gap between what the carrier approved and what the repair really costs.
Appraisal & estimating services
From one disputed roof to a multi-building HOA claim, every service is aimed at a valuation of your loss that stands up on its own.
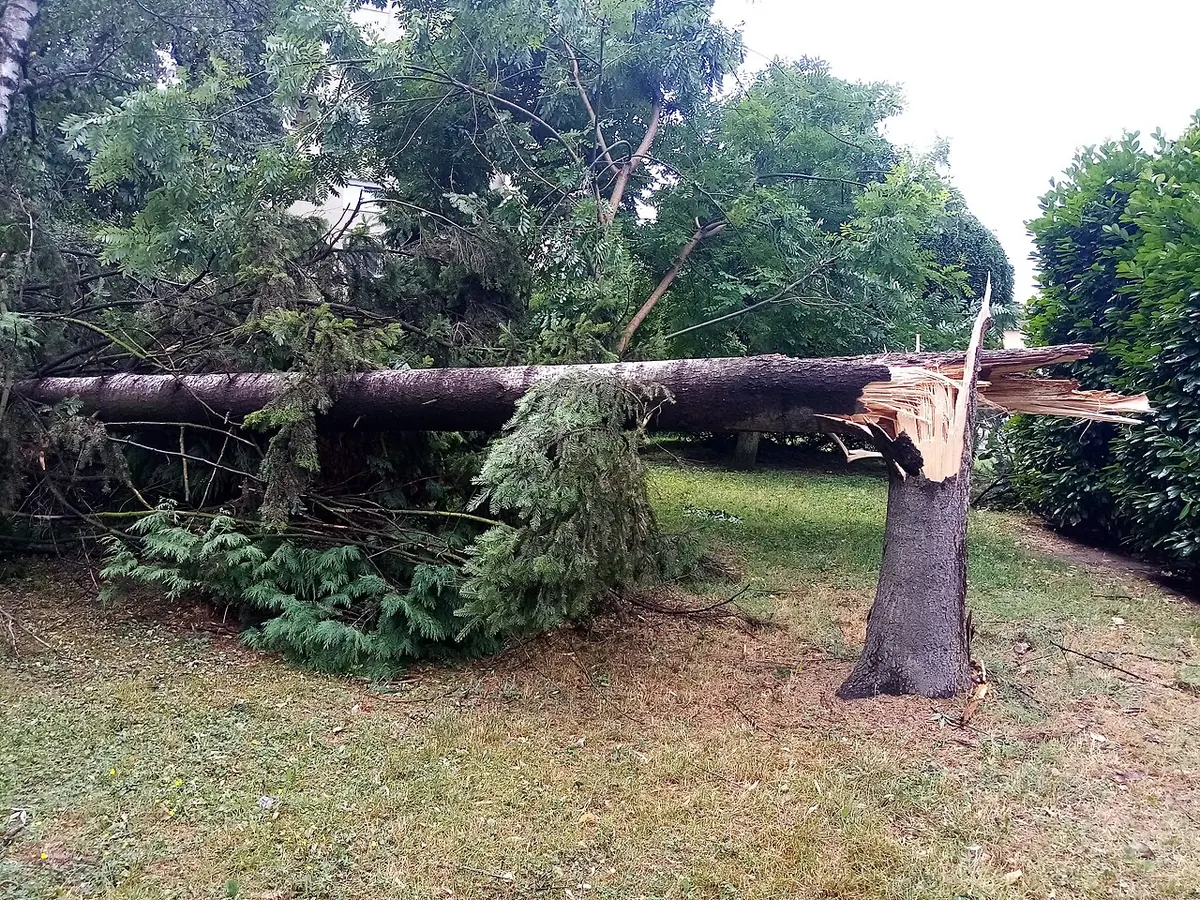
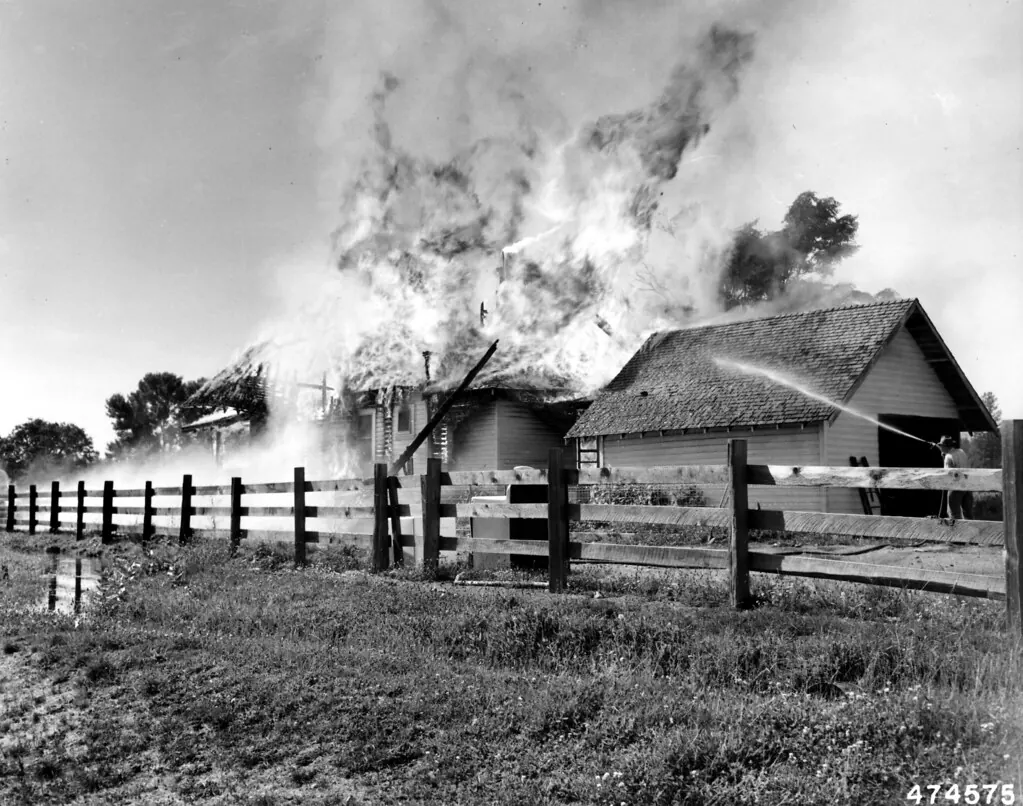
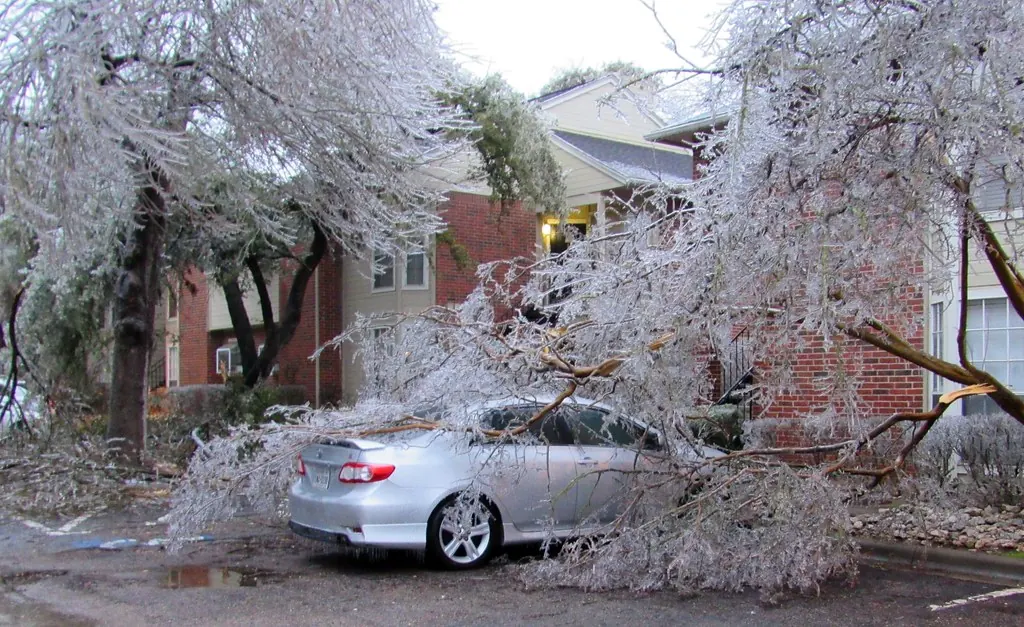
Arkansas claim calendar
Arkansas doesn’t have one storm season. It has four, and each leaves a different kind of claim behind. An Arkansas Insurance Appraiser prices each one with that history in mind.
How appraisal works
The appraisal clause turns an open-ended argument into a defined process with a binding result. Here is how Arkansas Insurance Appraiser takes a file from the first call to the award.
Confirm the carrier has accepted coverage and that the dispute is about the amount of loss, not whether the loss is covered.
Find the appraisal condition in your policy and note its deadlines, how the umpire is chosen and how costs are split.
Either side can demand appraisal in writing. The letter identifies the claim and the items in dispute.
Each side names a competent, impartial appraiser, usually within about 20 days of the demand.
The two appraisers try to agree on an umpire. If they can’t, either side can usually ask a court to appoint one.
The appraisers inspect, exchange estimates and work through the differences line by line.
Regional knowledge
Hail in Bentonville is not ice in Texarkana. An Arkansas Insurance Appraiser has to know how each part of the state’s weather shows up on a roof, and in an estimate.
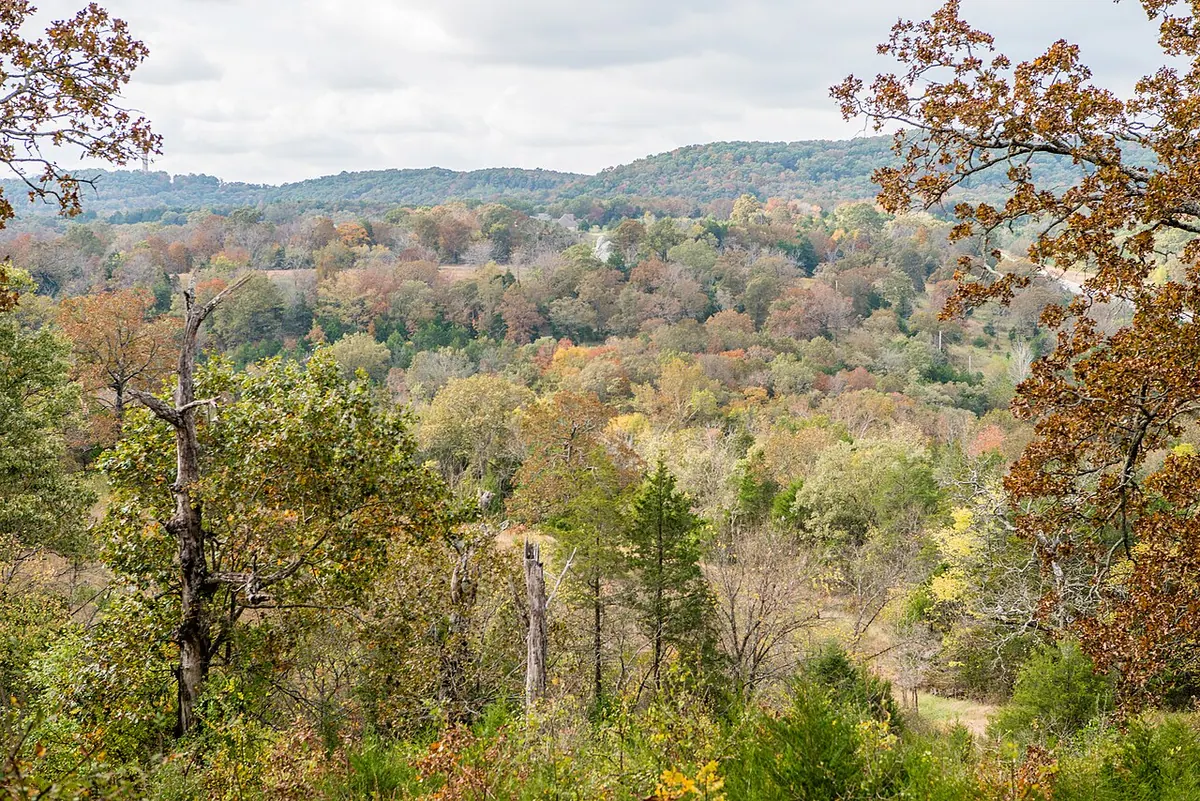
Fayetteville · Springdale · Rogers · Bentonville
The state’s busiest hail corridor and the core of the January 2009 ice storm. Fast growth means many young roofs, complex rooflines and discontinued products.
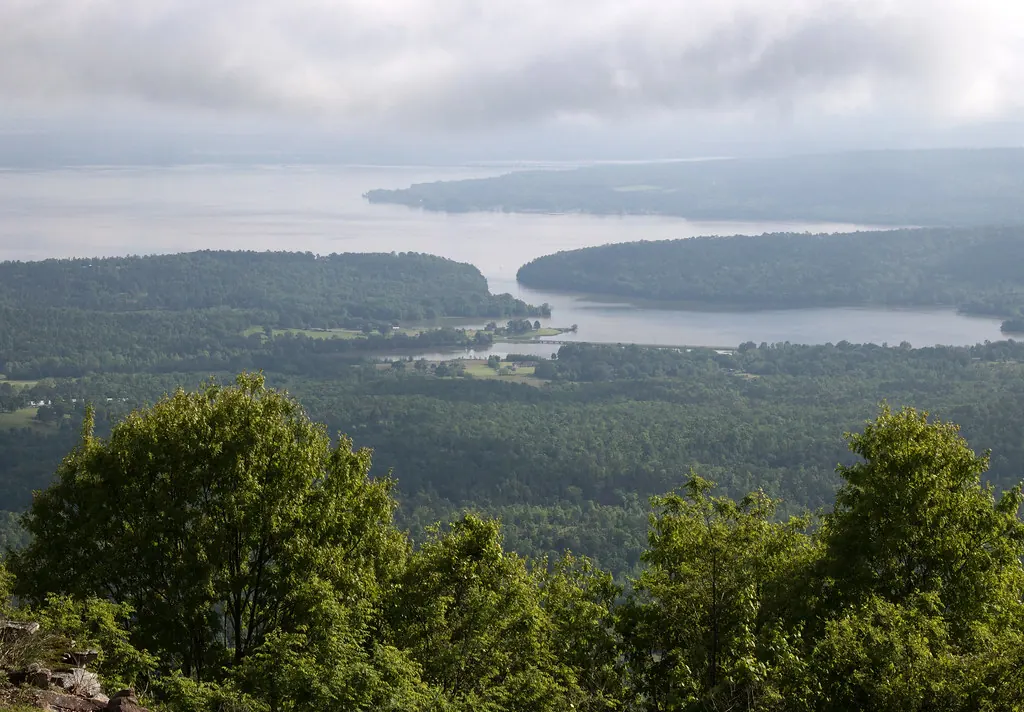
Fort Smith · Van Buren · Russellville · Conway
A natural storm track between the Ozarks and the Ouachitas. Tornadoes, straight-line winds and the 2019 river flood all left their mark here.
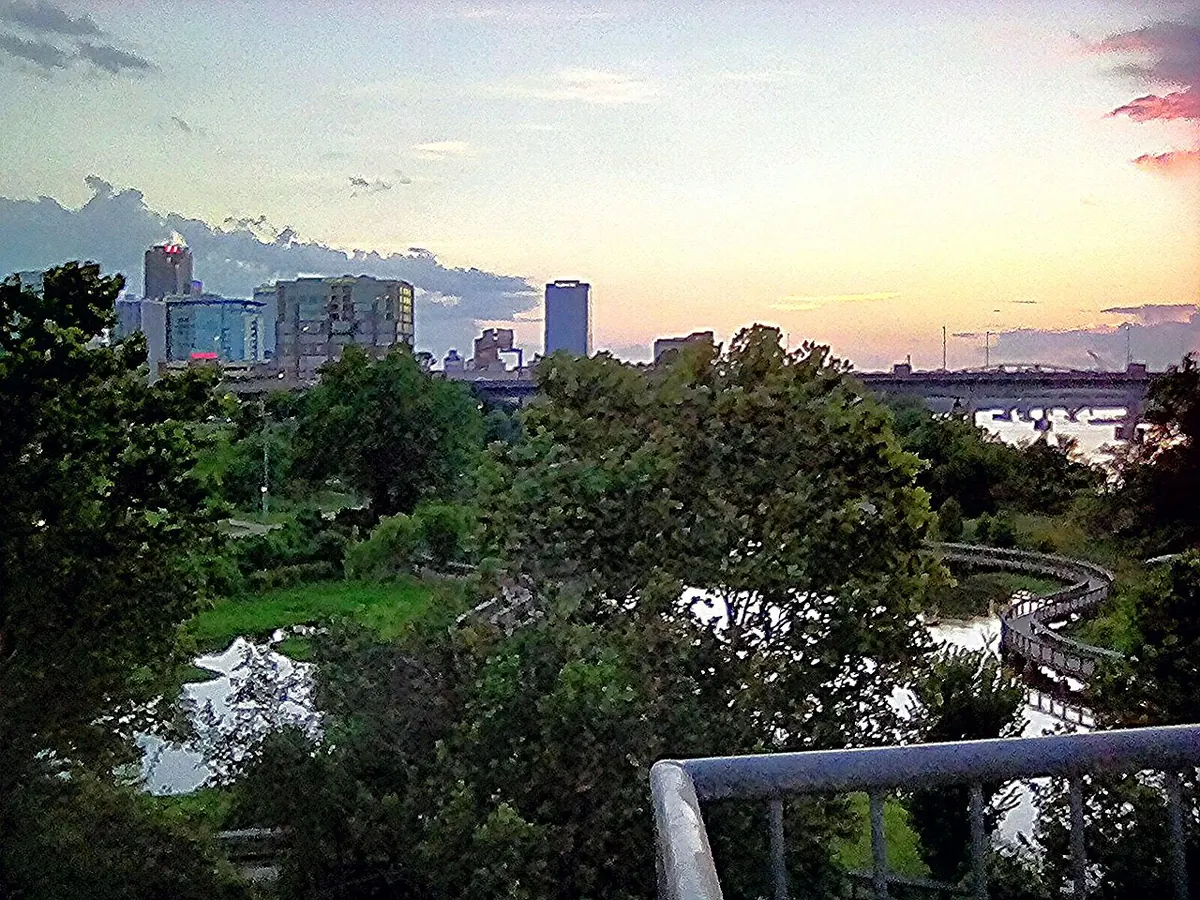
Little Rock · North Little Rock · Benton · Cabot
The metro area hit by the March 31, 2023 tornadoes, with historic homes, mid-century ranches and large commercial buildings side by side.
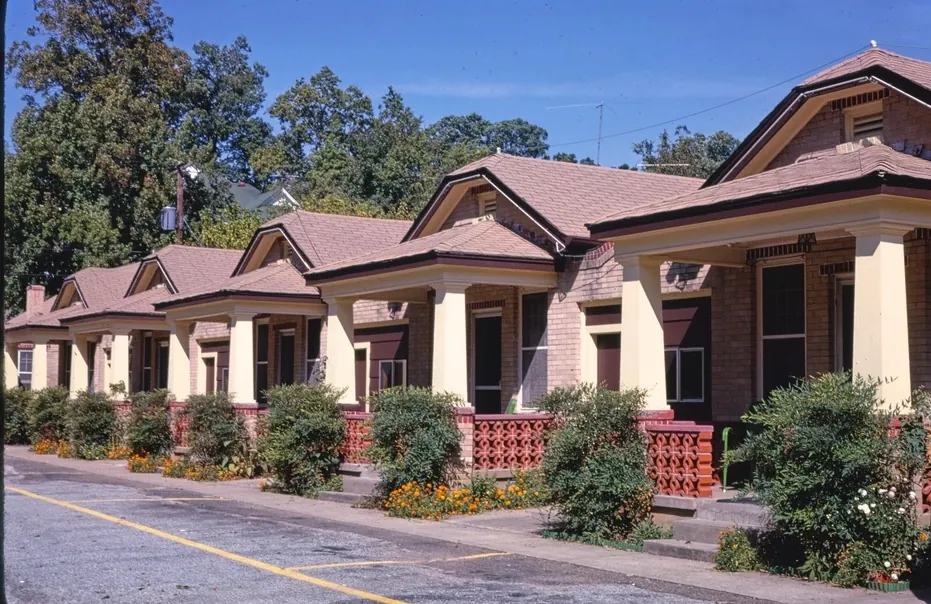
Hot Springs · Hot Springs Village · Mena
Wooded slopes, lakes and steep lots. Tree impacts, flash flooding and access costs shape claims in Garland, Montgomery and Polk counties.
Jonesboro · Pine Bluff · West Memphis · Helena
Flat, open farmland where storm systems intensify. Tornadoes and long-track straight-line winds hit homes, churches, shops and grain facilities.
Texarkana · El Dorado · Camden · Magnolia
Pine forest country where the December 2000 ice storm and Gulf hurricane remnants brought down thousands of trees onto roofs.
Quick gap check
Enter the two numbers you already have. If the difference is large, a conversation with an Arkansas Insurance Appraiser makes sense. If it’s small, a documented supplement request is often faster and cheaper.
The full claim gap & fee estimator adds appraiser and umpire fees and shows a break-even point.
Free & private
Seven calculators and planners that run entirely in your browser. Nothing you type is stored or sent.
 Estimator
 Calculator
 Calculator
 Calculator
 Planner
 Checklist
 Arkansas tool
Statewide service
We cover every county. These twelve communities are where Arkansas Insurance Appraiser works on claims most often.
Right tool for the job
Picking the right help first saves time and fees. Arkansas Insurance Appraiser will point you elsewhere when appraisal isn’t the answer.
| Question | Arkansas Insurance Appraiser | Public adjuster | Attorney |
|---|---|---|---|
| Main job | Value the amount of loss | Handle and negotiate the claim | Legal disputes and litigation |
| Best stage | Coverage accepted, number disputed | From first notice | Denials, bad faith, deadlines |
| Typical result | Two-signature award | Negotiated settlement | Settlement or judgment |
Questions
Plain answers about how appraisal works, what it costs and when it’s the wrong move.
An Arkansas Insurance Appraiser values property damage when you and your insurer agree the loss is covered but disagree on the cost. As your named appraiser we inspect, build an independent line-item estimate, work through the differences with the carrier’s appraiser and, if needed, present unresolved items to a neutral umpire.
No. A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question, the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage is accepted, you have the carrier’s estimate, and the gap between it and a qualified contractor’s estimate is meaningful, often more than about 10% or a few thousand dollars.
Generally yes, on the amount of loss for the items submitted, once two of the three panel members sign. That is why documentation matters before appraisal is demanded.
Each side usually pays its own appraiser and half of the umpire. Fees are agreed in writing before work starts, and the first conversation is free.
Yes. We work in all 75 Arkansas counties, with frequent work in Northwest Arkansas, the River Valley, central Arkansas, the Delta and south Arkansas.
Guides
Practical guides from Arkansas Insurance Appraiser on Arkansas policy language, documentation and claim strategy.
A plain-English walk through the appraisal condition found in most Arkansas property policies, and the mistakes that weaken it.
Your first check is usually actual cash value. How depreciation was calculated, including on labor, can change it by thousands.
Freezing rain is Arkansas’s quiet catastrophe. Here’s how ice storm claims work and where they get underpaid.
Before you sign off
A short review now can keep you from settling for less than the repair costs.
Start with a conversation
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing. No pressure and no obligation.
